A Distress Deal in Dubai costs more to close than the price you agree. Budget for the DLD transfer fee of 4% of sale value, a registration trustee fee, title deed and map fees, a developer NOC, agency commission, and, where a mortgage is involved, registration and release fees. Distressed purchases add further items, most often service charge arrears.
A gross discount is a headline. The net is what you underwrite.
Why this article cites its sources
Nearly every page online listing Dubai property fees states figures without saying where they came from. Several of those figures do not match the Dubai Land Department’s own published schedules.
The clearest example: a title deed fee of AED 580 is quoted widely, including on some of the most-read pages on this topic. I could not find AED 580 on any DLD page. The DLD itemises the title deed at AED 250, with map fees and small knowledge and innovation fees charged separately. The AED 580 figure looks like a bundled total that has been copied between sites until it acquired the appearance of an official rate.
I am flagging that rather than repeating it, because if a source is careless with a number you can verify, you should not trust it on a number you cannot.
The fee stack, line by line
DLD transfer fee: 4% of sale value. Worth knowing that DLD’s own schedule publishes this as a split, 2 per cent payable by the seller and 2 per cent by the buyer. Market practice in Dubai usually loads the full 4% onto the buyer. That is custom, not the published rule, and on a distressed deal where the seller has no cash it is effectively non-negotiable. Know the difference anyway. The schedule does not vary by passport either — overseas buyers pay the identical DLD fees.
Registration trustee fee: AED 4,000 plus VAT where sale value is AED 500,000 or above, and AED 2,000 plus VAT below that. VAT-inclusive, DLD’s mortgaged-property schedule shows these as AED 4,200 and AED 2,100.
Title deed: AED 250 for issuing the certificate.
Map and administrative fees: a unified map through Dubai Municipality at AED 225, an apartment map at AED 250, a villa map at AED 250, plus a knowledge fee of AED 10 and an innovation fee of AED 10.
Developer NOC: required in freehold areas, obtained as an e-NOC through the Dubai REST app. The fee varies by developer. Ranges circulate publicly, and figures attributed to specific developers circulate too, but I have not fetched a developer fee schedule so I am not going to publish a named figure. Ask the developer directly.
Agency commission: commonly 2% of purchase price plus 5% VAT. This is market custom, not a regulated rate. RERA recognises the convention but I found no official page fixing it, so treat anyone who tells you 2% is “the legal rate” as someone repeating what they were told.
Mortgage registration, if you are financing: 0.25% of the mortgage value. A small administrative addition of around AED 290 is widely reported by market sources, though I did not find it on the DLD page I read.
Where the seller has a mortgage, additional published lines apply: base service fee AED 1,000, knowledge fee AED 10, innovation fee AED 10, service fee AED 525, mortgage release procedure AED 1,290, and registrar release fee AED 315.
The costs that only appear on distressed deals
Service charge arrears. The one that most often breaks a deal’s economics. Unpaid charges are a lien on the unit under Article 32(a) of Law No. 6 of 2019, and the unit cannot be disposed of until they are paid. On a distressed sale the seller usually cannot clear them, so unless you negotiate otherwise the number lands on you.
Deferred maintenance. A distressed owner has had no budget for upkeep for as long as they have been distressed. Inspect and price the works, and hold a contingency for what you cannot see.
Vacancy carry. If the unit is empty, you carry service charges and any financing cost until it is let or sold.
Legal and conveyancing. Optional on a simple resale, and in my view not optional on a distressed one.
Valuation. Required if you are financing, and worth paying for even if you are not.
The February 2025 change that hits leveraged buyers
A change reported in early 2025 removed the ability to finance the DLD transfer fee and brokerage commission within a mortgage. UAE banks stopped including the 4% DLD fee and the 2% brokerage commission in the amount they would lend, effective 1 February 2025.
The effect, a leveraged buyer needs roughly 6% of the purchase price in additional cash beyond the down payment. On a distressed purchase where speed matters, that is a real constraint on what you can actually transact.
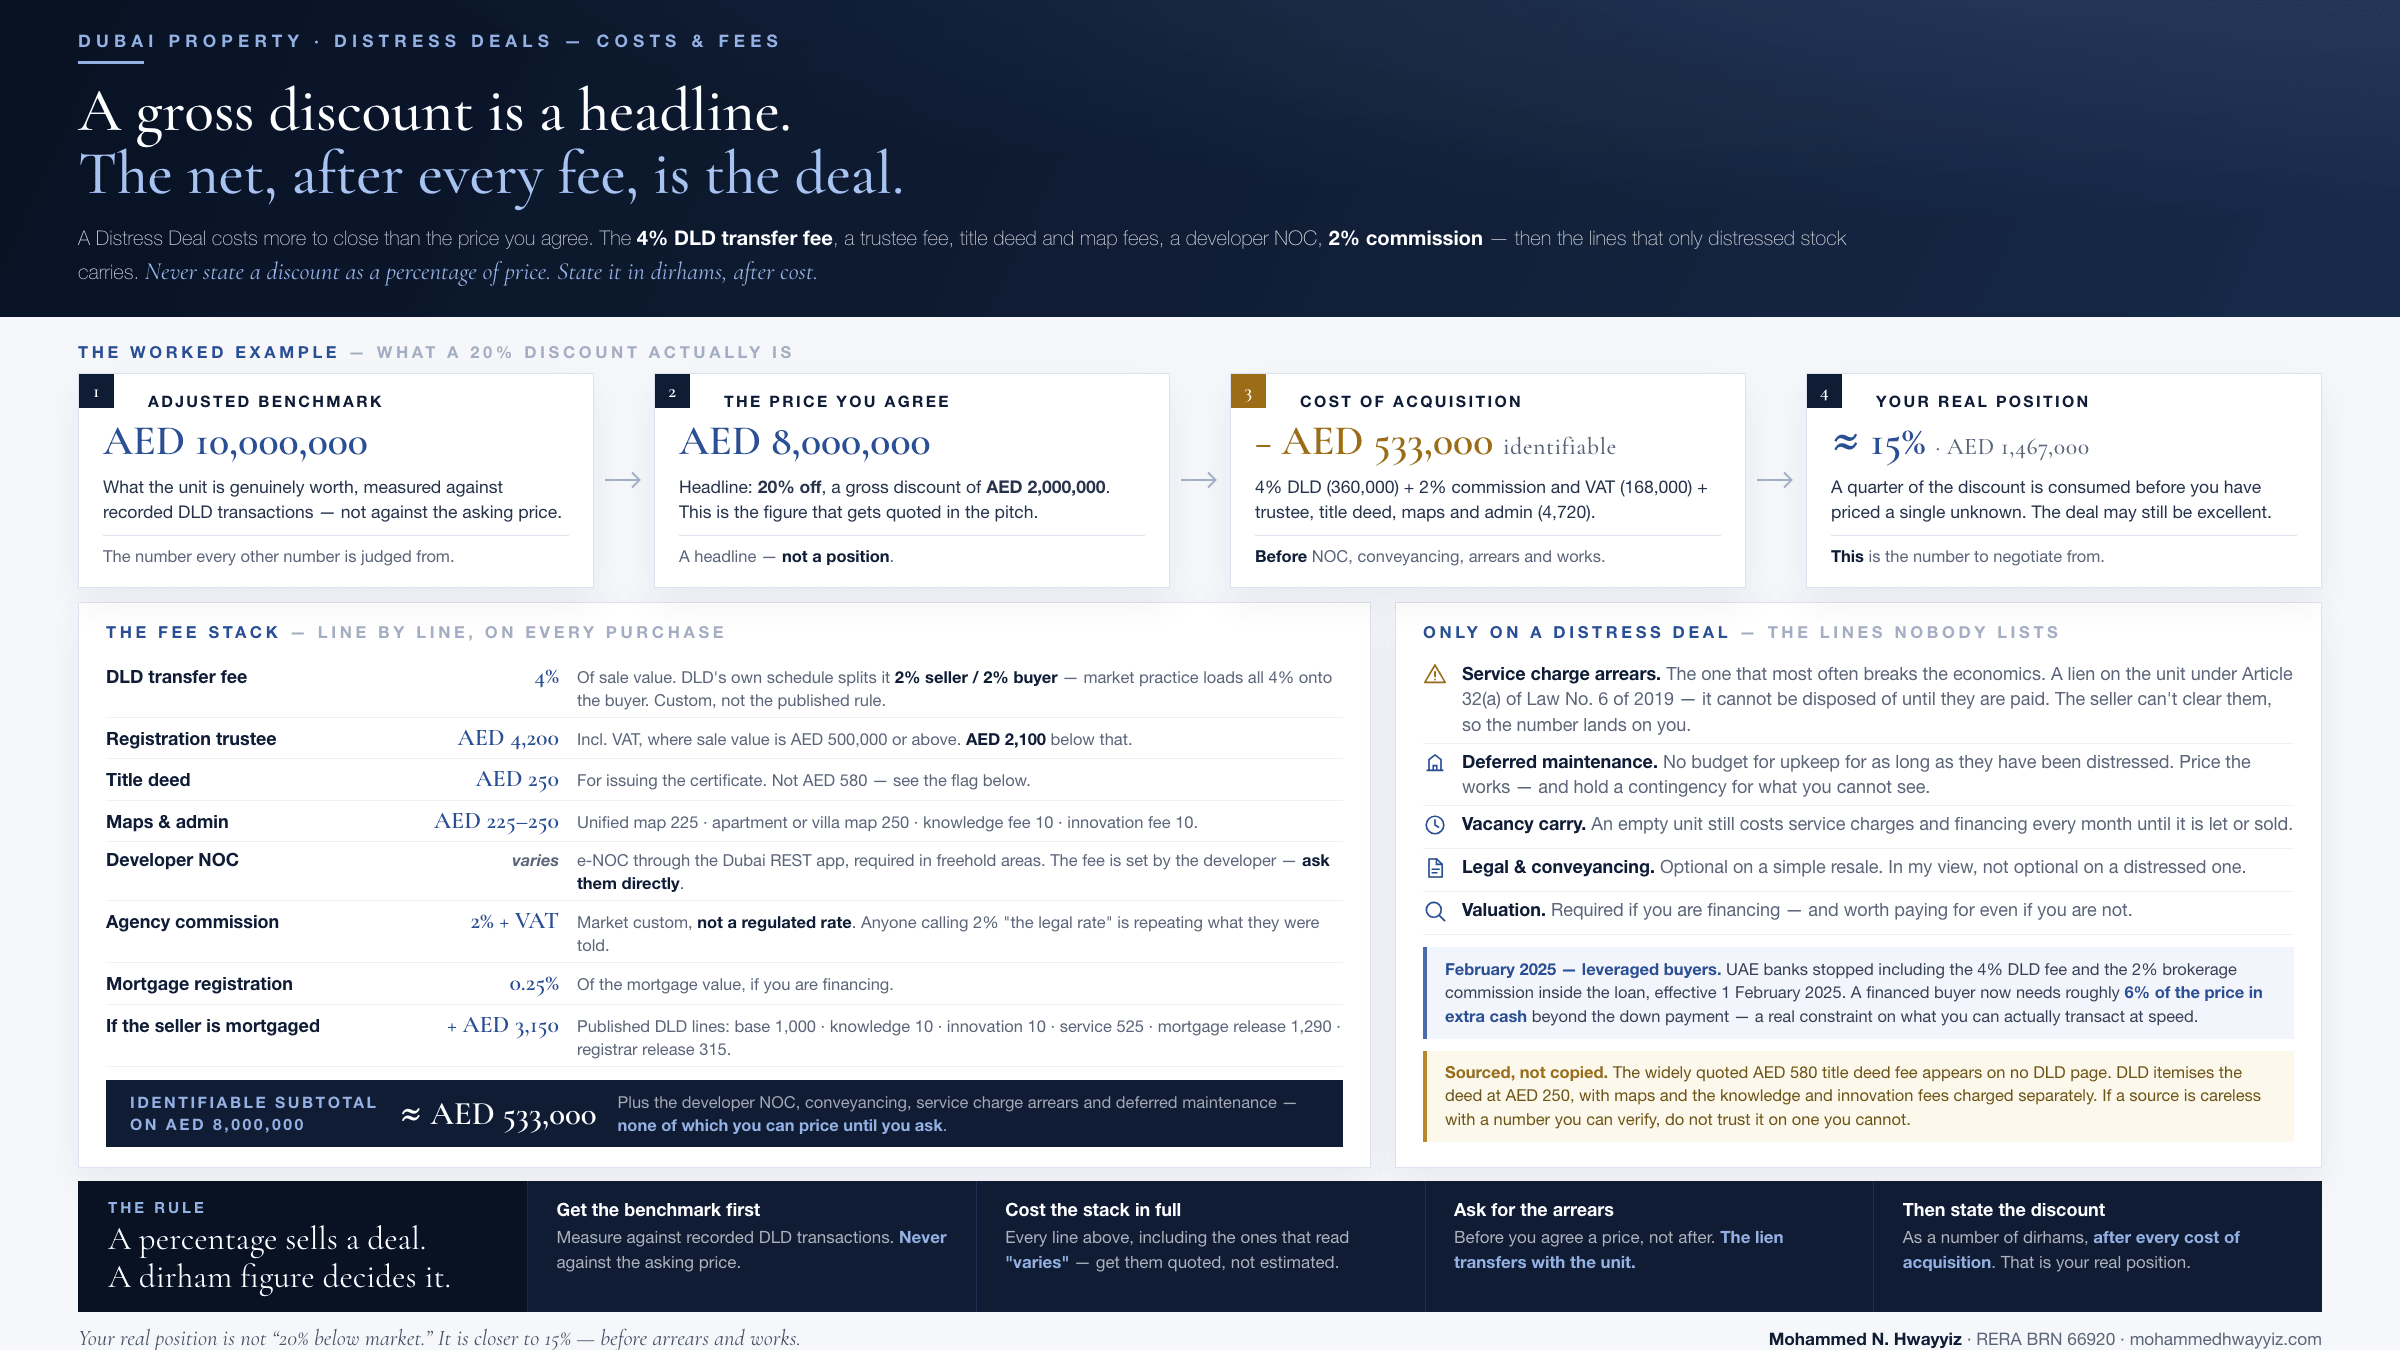
Worked example: what a 20% discount really is
Take a unit with an adjusted market benchmark of AED 10,000,000, offered at AED 8,000,000. The headline is a 20% discount, or AED 2,000,000.
Now build the cost side on the AED 8,000,000 purchase:
| Line item | Amount (AED) |
|---|---|
| DLD transfer fee, 4% | 360,000 |
| Registration trustee, incl. VAT | 4,200 |
| Title deed | 250 |
| Apartment map | 250 |
| Knowledge and innovation fees | 20 |
| Developer NOC | varies by developer |
| Agency commission, 2% + 5% VAT | 168,000 |
| Conveyancing | varies |
| Service charge arrears | unknown until you ask |
| Identifiable subtotal | ~532,720 plus NOC, conveyancing and arrears |
Against a AED 2,000,000 gross discount, roughly AED 533,000 of identifiable acquisition cost consumes about a quarter of it before you have accounted for the NOC, legal work, arrears, or any deferred maintenance.
The deal may well still be excellent. But your real position is not “20% below market.” It is closer to 15% before arrears and works, and possibly less after. That is the number to negotiate from.
The rule
Never state a discount as a percentage of price. State it as a number of dirhams after every cost of acquisition. The first version sells deals. The second version tells you whether to do one.
If you want a specific deal costed properly before you commit, that is what I do.