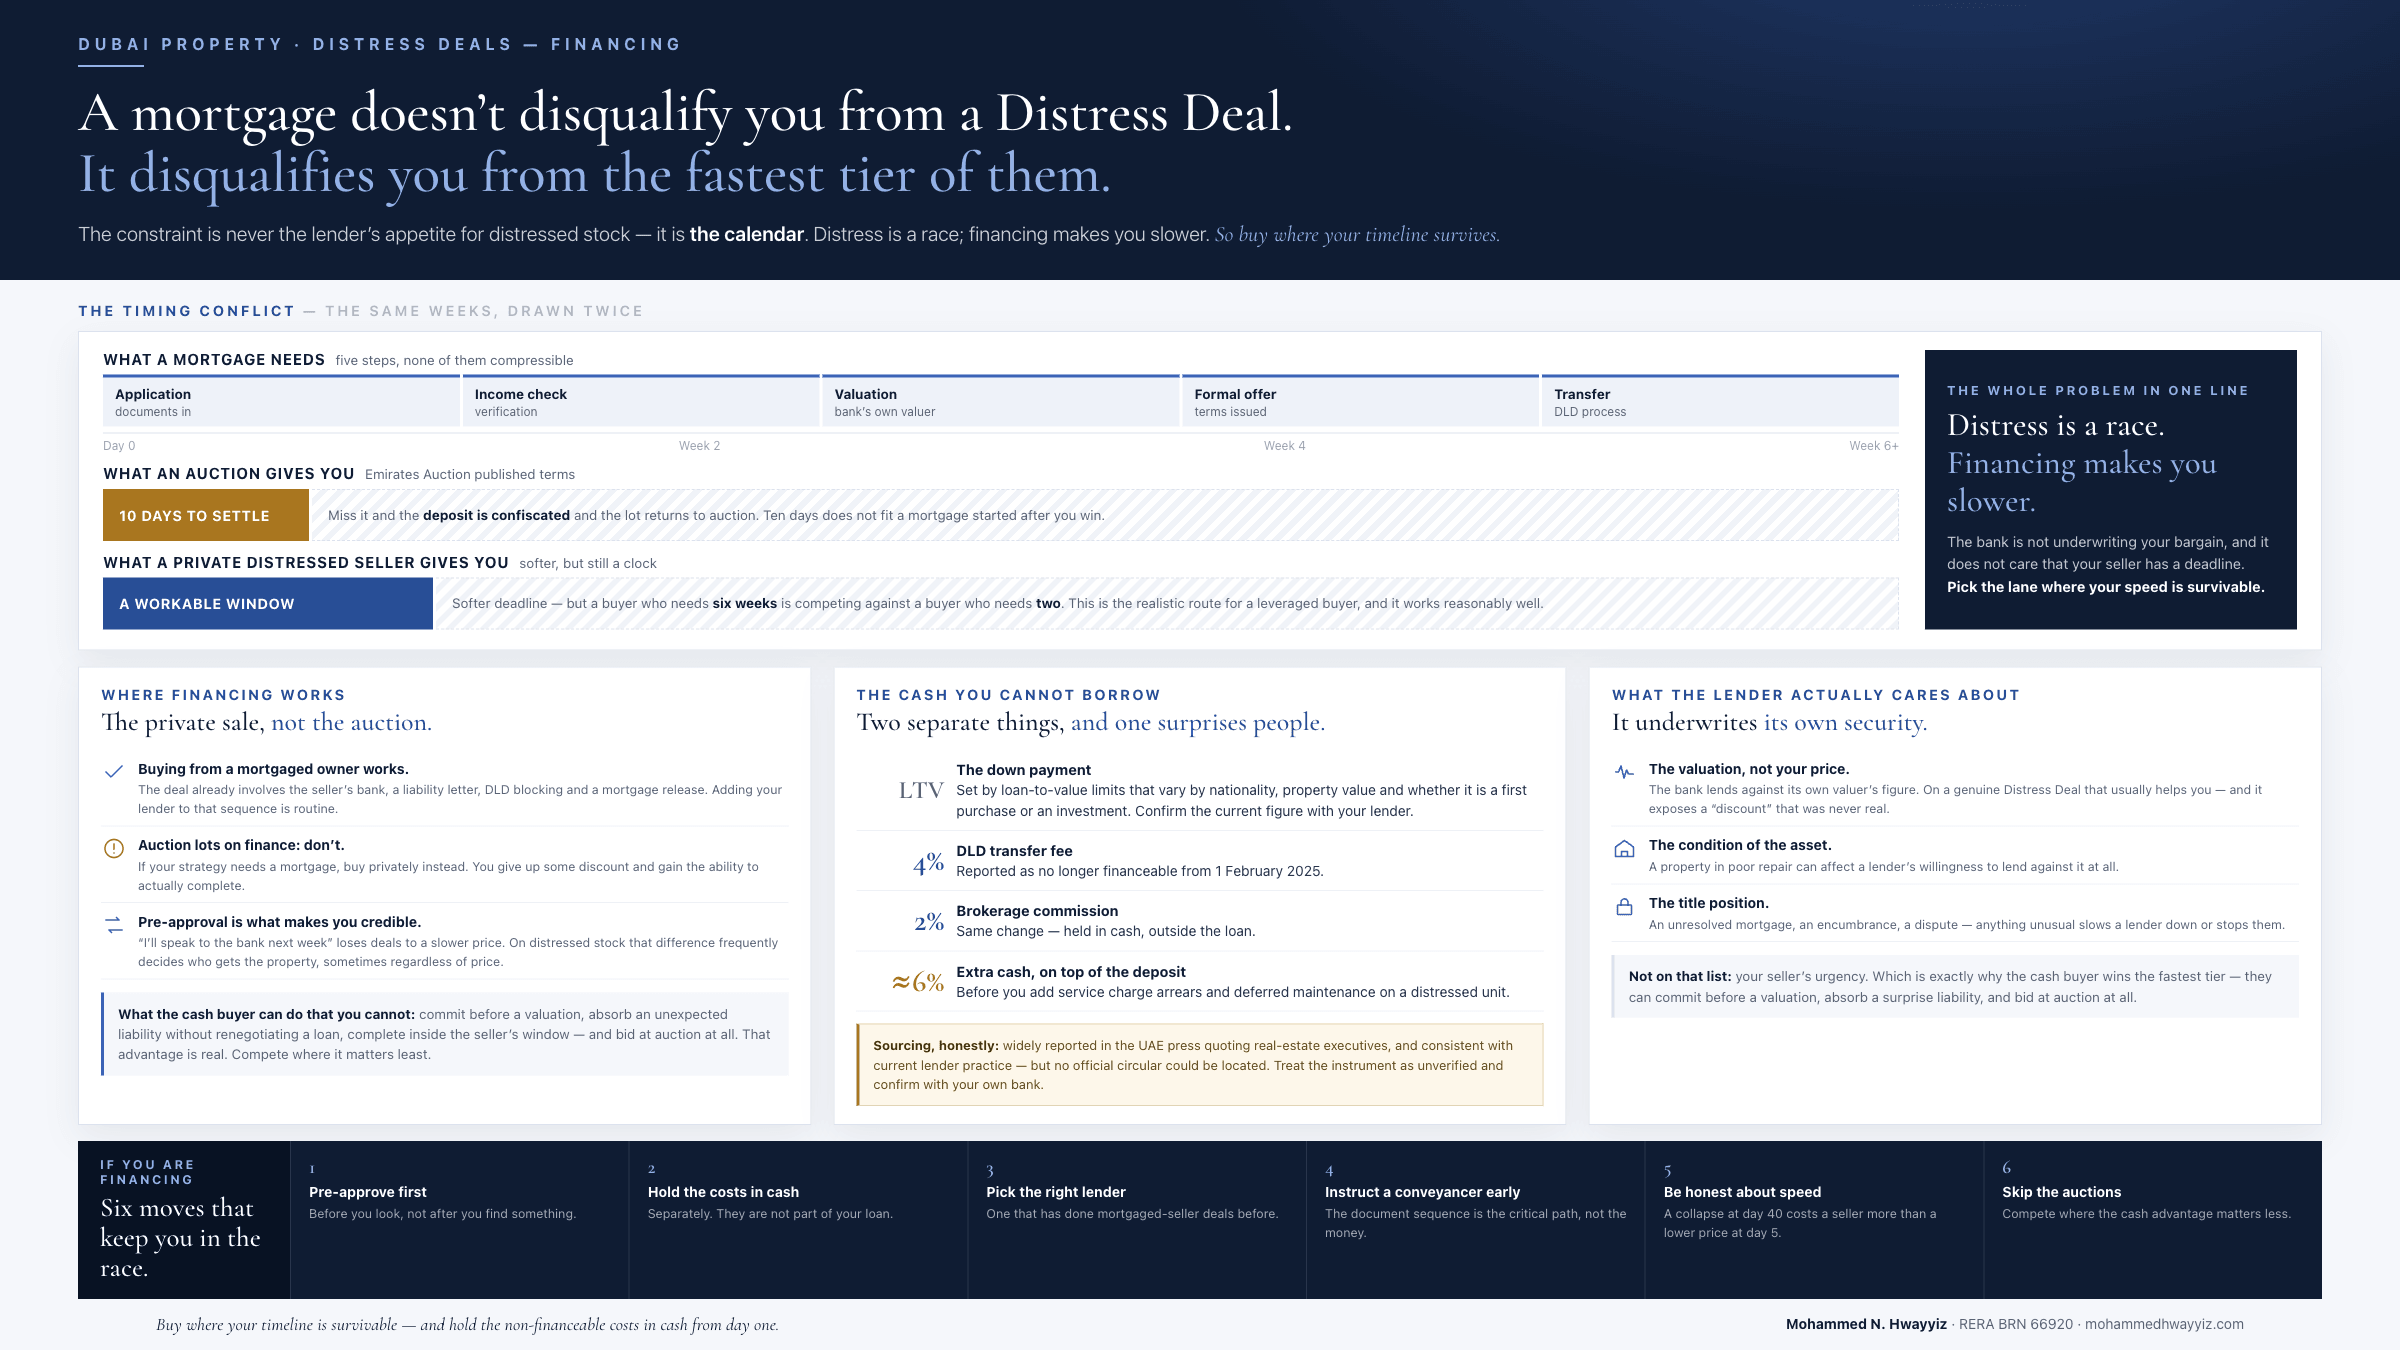
You can usually get a mortgage on a Distress Deal in Dubai when you are buying privately from a motivated or mortgaged seller. You usually cannot at auction, because auction settlement windows are far shorter than mortgage approval takes. The constraint is not the lender’s appetite for distressed stock. It is the calendar.
Distress is a race. Financing makes you slower. That is the whole problem in one line.
The timing conflict, stated properly
A Dubai mortgage involves an application, income verification, a lender-instructed valuation, a formal offer, and then the transfer process itself. Each step has a realistic duration and none of them can be compressed much.
Now look at what a distressed sale gives you.
| The clock | How long | What sets it |
|---|---|---|
| A Dubai mortgage | Six weeks or more | Application, income verification, valuation, formal offer, transfer. |
| At auction | 10 days | Fixed by the published terms. Miss it and the deposit is confiscated. |
| Private distressed sale | Softer, still real | Set by the seller's own clock, and by who else is bidding for it. |
At auction, Emirates Auction’s published terms require the winning bidder to pay the balance within 10 days from the date the bid is approved. If you miss it, the deposit is confiscated and the property returns to auction. Ten days does not accommodate a mortgage process started after you win.
On a private distressed sale, the deadline is softer but still real. The seller is selling because they are on a clock, and a buyer who needs six weeks is competing against a buyer who needs two.
Where financing works: the private distressed sale
This is the realistic route for a leveraged buyer, and it works reasonably well.
You are buying from an owner under pressure, frequently one who still has a mortgage of their own. The transaction already involves the seller’s bank, a liability letter, property blocking at a DLD trustee office, and a mortgage release. Adding your own lender to that sequence is normal, and conveyancers handle it routinely.
What makes the difference is preparation. A buyer with pre-approval in hand is a credible fast buyer. A buyer who will “speak to the bank next week” is not, and on a distressed deal that difference frequently decides who gets the property, sometimes regardless of price.
The cash requirement people underestimate
Two separate things determine how much cash you need.
The down payment. Dubai mortgage lending is subject to loan-to-value limits, which vary by whether you are a UAE national or an expatriate, by property value, and by whether it is a first purchase or an investment property. Confirm the current limits with your lender rather than relying on a figure from an article, including this one. Residency is not the gate people assume it is — non-resident buyers can purchase without a visa, though the lending terms tighten.
The costs you cannot finance. This is the part that catches people. As reported in early 2025, UAE banks stopped including the 4 per cent DLD transfer fee and the 2 per cent brokerage commission within mortgage financing, effective 1 February 2025.
I want to be precise about the sourcing on that. It was widely reported in the UAE press, quoting real estate executives, and it is consistent with current lender practice. I could not locate an official circular or a named issuing authority, so treat the underlying instrument as unverified and confirm with your own bank.
If it applies to you, the effect is roughly 6 per cent of purchase price in additional cash on top of the down payment. On a distressed purchase where you are also budgeting for possible service charge arrears and deferred maintenance, that changes what you can actually transact.
What lenders actually care about on a distressed unit
A lender is not underwriting your bargain. It is underwriting its own security. Three things matter to them:
The valuation. The bank instructs its own valuer, and lends against that figure, not against your purchase price. On a genuine Distress Deal this usually works in your favour, because the valuation may come in above what you are paying. But it can also expose a deal where the “discount” was never real, which is a useful second opinion.
The condition of the asset.A property in poor repair can affect a lender’s willingness to lend against it.
The title position. Anything unusual, an unresolved mortgage, an encumbrance, a dispute, slows a lender down or stops them.
Notice that a distressed seller’s urgency is not on that list. The bank does not care that your seller has a deadline.
How to be a financed buyer who still wins distressed deals
- Get pre-approval before you look, not after you find something. It is the single highest-leverage thing you can do, and it costs you nothing but time you have anyway.
- Hold the transaction costs in cash and separately. If you cannot finance the DLD fee and commission, they are not part of your loan calculation.
- Choose a lender familiar with mortgaged-seller transactions. The process involves the seller’s bank as well as yours, and a lender who has done it before moves faster.
- Instruct a conveyancer early. On a distressed deal the document sequence is the critical path, not the money.
- Be honest about your speed.If you cannot complete inside the seller’s window, say so and adjust the price, rather than agreeing a timeline you will miss. A collapsed deal at day 40 costs the seller more than a lower price at day 5, and they know it.
- Do not chase auction lots on finance. If your strategy needs a mortgage, buy from private distressed sellers instead. You give up some discount and gain the ability to actually complete.
The cash buyer’s advantage, quantified honestly
A cash buyer in this market is not simply faster. They can:
- Commit before a valuation.
- Absorb an unexpected liability without renegotiating a loan.
- Complete inside a seller’s window, which is the thing the seller is actually buying.
- Bid at auction at all.
That advantage is real and it is why cash buyers get the better distressed stock. If you are financing, accept it and compete somewhere the advantage matters less, which means private sales with a slightly longer runway rather than forced auction timelines.
The honest bottom line
Financing does not disqualify you from Distress Deals in Dubai. It disqualifies you from the fastest tier of them. Buy where your timeline is survivable, prepare so that it is as short as it can be, and hold the non-financeable costs in cash from the start.
If you want to know whether a specific deal is financeable before you commit, send it over.